
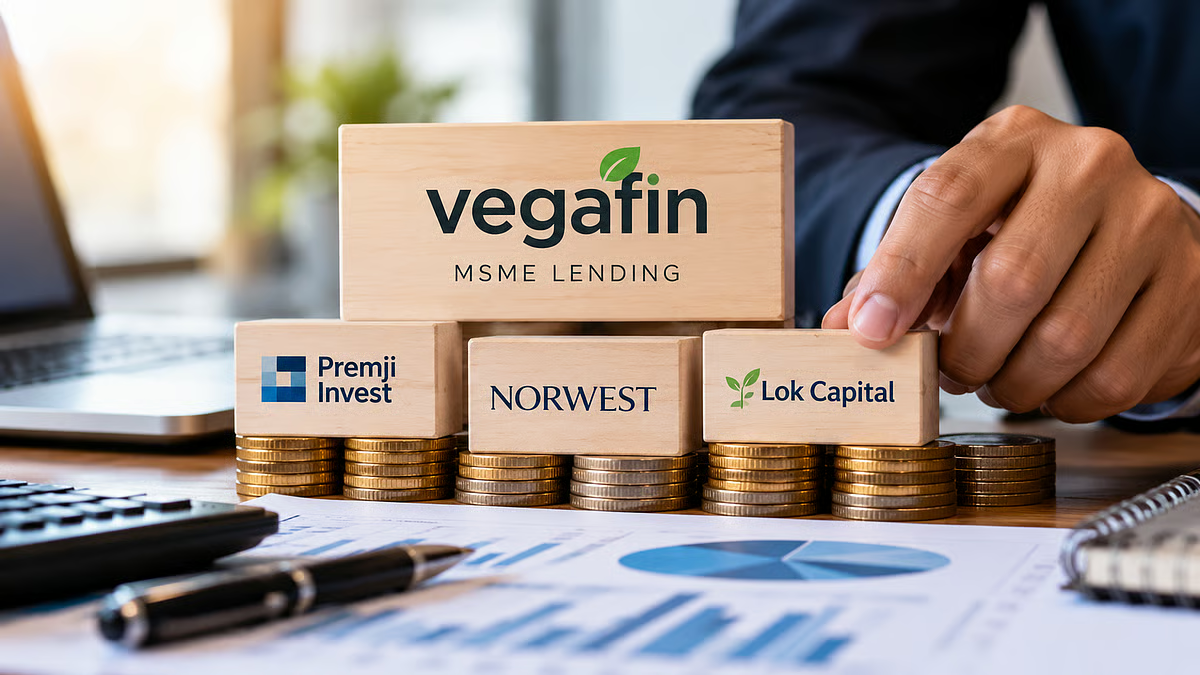
Vegafin has secured an investment commitment of up to ₹1,000 crore from Premji Invest, Norwest and Lok Capital to build an artificial intelligence-driven lending platform for India’s micro, small and medium enterprises. The move includes plans to acquire a majority stake in Bizloan.
Vegafin Attracts Major Investment for Small Business Lending
Indian financial services startup Vegafin is preparing to expand its presence in the micro, small and medium enterprises (MSME) lending market after attracting investment commitments of up to ₹1,000 crore from three major investors. Announced on October 21, 2026, the investment involves Premji Invest, Norwest and Lok Capital, which plan to support the development of a technology-led lending platform for small businesses across India.
Founded by Bijith Bhaskar, a former senior executive at ICICI Bank, Vegafin aims to combine artificial intelligence, digital lending processes and data-driven credit assessment to improve financing access for businesses that often struggle to obtain formal credit.
The proposed investment marks the beginning of the company’s effort to establish a broader MSME lending business. Rather than building its lending operations entirely from scratch, Vegafin has signed definitive agreements to acquire a majority stake in Bizloan, a Gurugram-based non-banking financial company specialising in secured loans to MSMEs.
The acquisition is expected to provide Vegafin with an existing lending operation, an established customer base and a branch network that can support its expansion plans.
Why India’s MSME Lending Market Matters
MSMEs play an important role in India’s economy, supporting employment, manufacturing, services and local entrepreneurship. From neighbourhood retailers and wholesalers to small manufacturing units and service providers, these businesses depend on regular access to working capital to maintain operations and expand.
However, access to formal credit remains a challenge for many smaller enterprises. Businesses with limited financial documentation, inconsistent cash flows or inadequate collateral may find it difficult to meet conventional lending requirements.
For example, a small hardware shop in Nagpur may need additional funds to purchase inventory before a busy business season. Similarly, a manufacturing unit in an industrial area may require financing to buy equipment or fulfil a large order. Without timely credit, these businesses could struggle to manage expenses or take advantage of new opportunities.
Such requirements have created opportunities for specialised lenders that understand small-business cash flows and can assess borrowers beyond traditional lending indicators.
Vegafin intends to address part of this demand by developing a lending model focused on secured MSME credit, efficient operations and improved risk assessment. Its success, however, will depend on its ability to identify creditworthy borrowers while maintaining responsible lending standards.
How Artificial Intelligence Could Change MSME Lending
One of Vegafin’s central plans is to use artificial intelligence and data-led underwriting to improve lending decisions. Credit underwriting refers to the process of assessing a borrower’s financial position, repayment capacity and risk before approving a loan.
Traditional lending assessments often rely on financial statements, credit histories, collateral and other documented information. These remain important, but they may not always provide a complete picture of smaller businesses with limited formal records.
Technology can help lenders analyse multiple data points, organise documentation and identify patterns that support credit assessment. Digital workflows can also reduce paperwork and make it easier to process applications.
Vegafin plans to use these capabilities to improve turnaround times, refine risk selection and reduce operating costs. The company also intends to maintain an on-ground distribution network rather than depend exclusively on digital channels.
This combination of physical branches and digital services is commonly described as a phygital model. It can help lenders serve business owners who need personal assistance while also benefiting from faster digital processes.
However, artificial intelligence does not automatically guarantee better lending outcomes. The quality of available data, the reliability of credit models and the ability to detect inaccurate information will remain important factors. Lenders must also manage privacy, security and the risk of unfair or incorrect decisions.
Bizloan Acquisition Provides an Existing Lending Base
Bizloan is central to Vegafin’s initial expansion strategy. Founded in 2018, the Gurugram-based NBFC operates through more than 35 branches across five states and manages assets under management of over ₹235 crore, according to reports published on October 21.
An existing lending business can offer several advantages to a new platform. It provides operational experience, an established loan portfolio, relationships with borrowers and a physical distribution network. These assets can help a company begin lending sooner than it might if it were establishing every part of the business independently.
The acquisition may also provide Vegafin with a foundation for testing and improving its technology-led credit assessment processes.
Bizloan’s existing investors include the Michael & Susan Dell Foundation, BLinC Invest and Mohan Enterprises. Under the announced arrangement, BLinC Invest will remain invested, while the Michael & Susan Dell Foundation and Mohan Enterprises will exit their investments.
The transaction’s financial value has not been publicly disclosed in the reports reviewed. The acquisition is subject to regulatory approvals and customary closing conditions, meaning completion should not be assumed until the relevant requirements have been met.
What the Investment Means for Small Businesses
For India’s small businesses, the significance of the investment will ultimately depend on whether the new platform can deliver useful credit products at reasonable costs.
Smaller enterprises frequently need financing for inventory, equipment purchases, business expansion and working capital. Delays in accessing credit can affect their ability to fulfil orders, pay suppliers or maintain sufficient stock.
A technology-led lender could potentially make applications easier to process and help businesses receive lending decisions more quickly. A broader branch network could also help reach customers in smaller cities and semi-urban markets where access to specialised financial services may be uneven.
Vegafin’s founder has indicated plans to focus on secured loans in the range of ₹8 lakh to ₹30 lakh, targeting businesses such as grocery stores, hardware shops, pharmacies and other small enterprises. The company has also outlined plans to expand into additional states and grow its lending portfolio.
These plans could create opportunities for borrowers who need medium-sized business loans. However, faster processing should not be confused with guaranteed approval, and secured lending may require borrowers to provide acceptable collateral.
Businesses will still need to assess interest rates, processing fees, repayment schedules and the consequences of default before accepting a loan.
Competition and Execution Will Determine Future Growth
India’s MSME lending market includes banks, NBFCs, fintech platforms and other specialised financial institutions. Competition is likely to depend on how effectively lenders balance customer acquisition, borrowing costs, credit quality and operational efficiency.
Vegafin’s proposed investment gives it financial backing to build its platform, while the Bizloan acquisition provides an existing operating base. Its technology-led approach could help differentiate the business if it produces measurable improvements in credit assessment and service delivery.
Nevertheless, scaling a lending operation involves risks. Poor underwriting can lead to loan defaults, while aggressive expansion can increase operating expenses and weaken credit quality. Smaller businesses may also experience seasonal fluctuations, delayed payments from customers and changes in demand.
The company’s ability to expand responsibly will therefore be as important as its ability to distribute loans. Investors and market observers are likely to assess the quality of its loan portfolio, repayment performance, operating costs and progress in reaching underserved businesses.
The planned investment reflects investor interest in technology-enabled financial services and the financing needs of India’s small-business sector. Whether Vegafin can turn that backing into a sustainable lending business will become clearer as the acquisition progresses and the platform begins to scale.
Key Takeaways
- Premji Invest, Norwest and Lok Capital plan to invest up to ₹1,000 crore in Vegafin.
- Vegafin has signed agreements to acquire a majority stake in Bizloan, an NBFC focused on secured MSME lending.
- The company plans to combine AI-driven credit assessment, digital workflows and physical distribution.
- Its long-term success will depend on responsible lending, credit quality, affordable financing and sustainable expansion.
Frequently Asked Questions
1. What is Vegafin?
Vegafin is an MSME-focused lending platform founded by former ICICI Bank executive Bijith Bhaskar. It aims to use artificial intelligence, data-led underwriting and digital processes to expand access to business credit.
2. Who is investing in Vegafin?
Premji Invest, Norwest and Lok Capital have announced plans to invest up to ₹1,000 crore in the platform.
3. Why is Vegafin acquiring Bizloan?
The acquisition is intended to provide Vegafin with an established NBFC, an existing secured lending portfolio and a branch network that can support its expansion.
4. Will the investment guarantee easier loans for small businesses?
No. The investment may help Vegafin expand its lending capabilities, but loan approval will depend on eligibility, repayment capacity, credit assessment, collateral requirements and the lender’s policies.


Leave a comment