
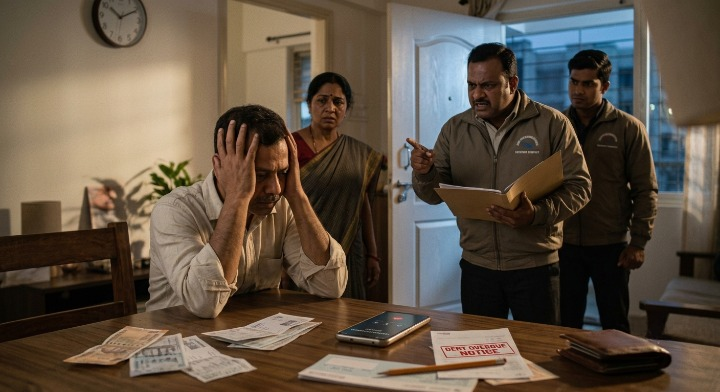
A borrower misses two EMIs after a salary cut. Another unexpected expense arrives, and a third payment becomes difficult to manage. Soon, calls from the lender begin. Embarrassed and overwhelmed, the borrower stops answering, hoping the situation will somehow improve.
But the outstanding dues remain, and so does the uncertainty.
For many Indians facing debt, the hardest part is not just the money owed. It is the feeling of losing control over their lives.
Could an earlier conversation with the lender have made the situation easier to manage?
What RBI Data Reveals About Borrower Complaints
According to the Reserve Bank of India’s Annual Report 2024–25, its Ombudsman offices received approximately 2.96 lakh complaints during the financial year, compared with 2.93 lakh in 2023–24. These complaints covered various banking issues, including loans and advances, credit cards and digital banking, rather than recovery harassment alone.
The RBI has also issued instructions prohibiting regulated lenders and their recovery agents from using intimidation, publicly humiliating borrowers, intruding on family privacy or making threatening calls. Recovery calls are restricted before 8 a.m. and after 7 p.m.
Recovering legitimate dues does not justify treating borrowers unfairly.
Why Borrowers Sometimes Stop Responding
Financial stress can make even a simple conversation difficult. Borrowers may fear being judged, may not know what to say or may be waiting for their income to recover.
However, silence does not resolve outstanding dues. Timely communication can create an opportunity to explain changed financial circumstances and ask the lender about possible repayment arrangements.
This does not guarantee that recovery calls will stop or revised terms will be approved, but it can help borrowers approach the situation with greater clarity.
Repayment Pressure and Harassment Are Not the Same
Lenders can contact borrowers about overdue payments and pursue recovery through lawful means. However, missing an EMI does not mean a borrower must accept threats, intimidation or public humiliation.
Borrowers who experience inappropriate recovery conduct should maintain records of calls and messages and raise complaints through the lender’s official grievance channel. If the issue remains unresolved, they can explore the applicable RBI complaint-redressal process.
A complaint about recovery conduct and an outstanding repayment obligation are separate matters that may need to be addressed independently.
How AdvoExpert Supports Borrowers Facing Recovery Harassment
For borrowers dealing with persistent recovery calls, the challenge often goes beyond understanding their outstanding dues. They may need help understanding their rights, responding appropriately and identifying the next practical step.
AdvoExpert, a borrower-focused debt-resolution firm, provides personalised, one-to-one guidance to individuals and families across India facing loan repayment difficulties and recovery-related concerns.
Rather than recommending the same solution to everyone, AdvoExpert considers each borrower’s circumstances, including income, essential expenses, outstanding loans and repayment capacity. Its support helps borrowers understand relevant options, risks and timelines before making important financial decisions.
Where recovery interactions appear inappropriate, borrowers can also receive guidance on documenting incidents, understanding applicable recovery rules and approaching appropriate grievance-redressal channels. Depending on the circumstances, this may include guidance on DND requests where relevant, although such requests do not automatically stop legitimate loan-recovery communications.
For families struggling with multiple lenders, financial uncertainty or persistent recovery pressure, having someone explain the situation and possible next steps can make the process less overwhelming.
Through its debt-resolution services and personalised borrower guidance, AdvoExpert aims to help people make informed decisions while protecting their dignity. Depending on individual circumstances, available options may include regular repayment, exploring restructuring with a lender or assessing whether settlement is appropriate. Outcomes depend on the case and the lender’s decision; no single option is right for everyone.
A Difficult Situation Should Not Become a Silent One
Debt can make people feel ashamed, isolated and afraid of being judged. But avoiding the problem rarely makes the outstanding amount disappear.
If repayments are becoming difficult, review your finances, communicate with lenders where possible, keep written records and avoid making promises you cannot realistically keep. If recovery interactions cross the line into intimidation, appropriate grievance channels are available.
Financial difficulty may change a person’s ability to pay. It should never take away their dignity or their right to be treated fairly.
This article is for general awareness and does not constitute legal or financial advice. Available options and complaint remedies depend on individual circumstances and applicable regulations.



Leave a comment