
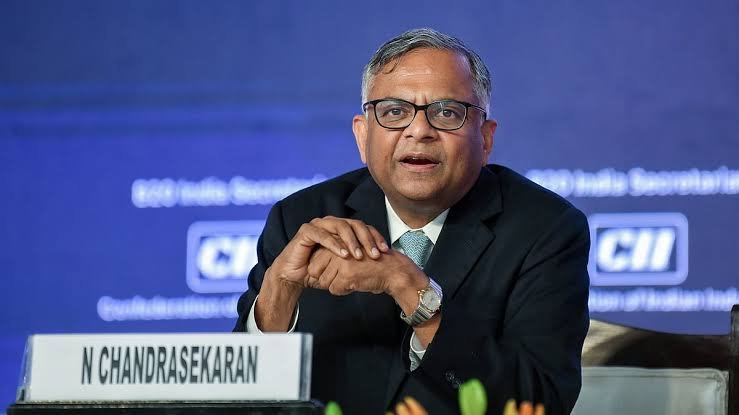
The Tata Sons listing debate has gained fresh momentum after the Reserve Bank of India (RBI) reiterated that the holding company of the Tata Group must comply with regulations applicable to Upper Layer Non-Banking Financial Companies (NBFCs), including mandatory stock market listing. The November 16 communication puts the issue back in focus ahead of an important board meeting scheduled for November 26, 2026. The development could have implications for corporate governance, shareholder rights and the regulatory treatment of large Indian business groups.
RBI Reiterates Mandatory Listing Requirement for Tata Sons
The Reserve Bank of India has strengthened its position on the proposed listing of Tata Sons through a communication sent to the company’s Chief Financial Officer on November 16, 2026.
The letter followed an October 6 communication from Tata Sons seeking regulatory guidance on compliance with applicable RBI regulations. According to reports published by Business Standard and other financial news organisations, the regulator observed that the company had not identified a specific regulation or guideline requiring clarification. However, it inferred from discussions at the company’s board level that the request was connected to the proposed listing.
The RBI subsequently advised Tata Sons to comply with all applicable regulations, guidelines and directions governing Upper Layer NBFCs, explicitly including the requirement to list its shares.
This communication is significant because it removes much of the ambiguity surrounding the regulator’s position. The latest letter does not announce a fresh listing deadline, but it reinforces the company’s existing regulatory obligations.
The development also comes after the RBI rejected Tata Sons’ application to surrender its registration as a Core Investment Company in September 2026, leaving the company subject to the applicable NBFC regulatory framework.
Why Tata Sons Falls Under the Upper Layer NBFC Category
Tata Sons is the principal holding company of the Tata Group. It owns stakes in several major businesses, including Tata Consultancy Services, Tata Motors, Tata Steel and other companies operating across different industries.
Its role extends beyond conventional business ownership. As the group’s holding company, Tata Sons oversees investments across sectors such as automobiles, information technology, steel, aviation, consumer products and financial services.
The RBI introduced a scale-based regulatory framework for NBFCs to strengthen supervision of financial institutions based on their size, interconnectedness and potential impact on the financial system.
Under this framework, certain large NBFCs are placed in the Upper Layer category. These companies face additional regulatory requirements because their operations and financial connections can have wider implications for the economy.
Tata Sons was classified as an Upper Layer NBFC in September 2022. Under the applicable framework, companies placed in this category are required to list their shares within three years of classification.
This made September 30, 2025, the applicable listing deadline for Tata Sons. However, the company remained unlisted while pursuing regulatory options to move outside the NBFC framework.
The RBI’s latest communication indicates that the regulator continues to expect compliance with the listing requirement.
Why Tata Sons Tried to Avoid a Public Listing
Tata Sons has historically operated as a privately held holding company. Unlike several of its major subsidiaries, its shares are not traded on public stock exchanges.
A stock market listing would introduce a significant change in how the holding company operates. It would bring greater public disclosure obligations, wider shareholder participation and additional scrutiny of its financial performance and corporate decisions.
In March 2024, Tata Sons approached the RBI seeking voluntary surrender of its registration as a Core Investment Company. The move was linked to its efforts to exit the NBFC regulatory framework and avoid the mandatory listing requirement.
The company had also repaid its outstanding debt, a development relevant to its efforts to reduce its exposure to certain regulatory requirements.
However, the RBI rejected the deregistration application on September 11, 2026, after examining the request. This decision meant that Tata Sons could not use the proposed deregistration route to escape the existing Upper Layer NBFC obligations.
The company subsequently sought further regulatory guidance in October. The RBI’s November 16 response has now reiterated that compliance must include listing.
Tata Trusts and Shapoorji Pallonji Have Different Positions
The Tata Sons listing debate is not only a regulatory issue. It also reflects differing interests among the company’s major shareholders.
Tata Trusts collectively hold approximately 66 per cent of Tata Sons. The trusts play a central role in the ownership structure of the Tata Group and support philanthropic activities through their investments and institutional work.
Tata Trusts chairman Noel Tata has opposed a public listing. The position reflects concerns about preserving the group’s existing ownership structure, long-term business philosophy and ability to make decisions without the pressures associated with public markets.
On the other side, the Shapoorji Pallonji Group holds approximately 18.37 per cent of Tata Sons and has supported the listing route.
For the Shapoorji Pallonji Group, a public listing could potentially provide liquidity and create a clearer market valuation for its investment. The group’s stake in Tata Sons is a significant financial asset, and the possibility of unlocking its value has remained an important part of the discussion.
The difference between these shareholder positions has brought the question of ownership, liquidity and long-term corporate control into sharper focus.
The disagreement also demonstrates how regulatory decisions can influence discussions between shareholders, particularly when a privately held company has a complex ownership structure.
What a Tata Sons IPO Could Mean for Investors
If Tata Sons eventually proceeds with a public listing, it could become one of the most closely watched corporate market developments in India.
The company’s portfolio includes businesses with significant market presence across multiple sectors. Its investment holdings could make the valuation process particularly important for institutional and retail investors.
A listing would provide investors with an opportunity to assess Tata Sons as a separate investment rather than gaining exposure to individual Tata companies through their respective shares.
However, determining the company’s valuation would not be straightforward.
A holding company valuation generally depends on the market value of its investments, liabilities, corporate expenses, cash flows and the structure of its ownership. Investors may also consider the difference between the value of underlying investments and the market value assigned to the holding company.
A public offering would also require disclosures about the company’s financial position, business structure, risks and related-party transactions in accordance with applicable requirements.
For retail investors, the development could create a new investment opportunity. However, a possible listing should not automatically be interpreted as a guarantee of attractive returns. The final valuation, shareholding structure and market conditions would remain important considerations.
As of November 17, 2026, the RBI has reiterated the listing requirement but has not announced a new public offering date or share price.
Corporate Governance and Regulatory Accountability in Focus
The Tata Sons case carries implications beyond the Tata Group because it highlights the relationship between corporate ownership structures and financial regulation.
Large business groups often operate through multiple subsidiaries, holding companies and investment entities. These structures allow companies to manage businesses across different sectors while maintaining a central ownership framework.
However, when a holding company meets the criteria for a regulated financial entity, its ownership structure does not automatically exempt it from regulatory obligations.
The RBI’s scale-based regulatory framework is intended to ensure that large and systemically important NBFCs face appropriate levels of supervision.
The Tata Sons issue therefore raises a broader question: should large corporate holding companies receive different regulatory treatment because of their historical ownership structures, or should the same rules apply when they meet the prescribed classification criteria?
The regulator’s latest communication supports the principle that applicable regulatory requirements must be followed.
For other Indian business groups, this serves as an important reminder that corporate restructuring, debt reduction or changes in ownership arrangements must be evaluated within the boundaries of existing regulations.
November 26 Board Meeting Could Become a Key Moment
The next important development is expected at the Tata Sons board meeting scheduled for November 26, 2026.
The RBI’s latest communication is likely to remain an important subject of discussion as directors consider the company’s regulatory position and available options.
The board’s earlier discussions have already highlighted differences over the proposed listing and the company’s future ownership structure.
A key question is whether Tata Sons will proceed with preparations for a public listing or continue examining possible restructuring options.
Any alternative arrangement would need to satisfy the applicable legal and regulatory requirements. The RBI’s latest communication does not itself approve or reject a new restructuring proposal.
The November 26 meeting could therefore provide greater clarity on the company’s next steps. However, an immediate IPO announcement should not be assumed.
The outcome will depend on the board’s decisions, shareholder positions and the regulatory framework governing the company.
What the Tata Sons Listing Debate Means for India’s Business Environment
The Tata Sons listing debate is an important case study for India’s corporate sector. It demonstrates how financial regulation can influence even established business groups with decades of private ownership.
For businesses in smaller cities, the issue may appear distant from everyday commercial activity. However, the outcome could influence investor confidence, corporate governance expectations and the broader relationship between regulators and large business houses.
India’s financial markets are becoming increasingly important for businesses seeking capital, improving transparency and attracting institutional investment.
A possible Tata Sons listing would bring additional attention to how holding companies are valued and how large corporate groups balance shareholder interests with long-term business objectives.
It could also encourage other companies to review their regulatory classifications and compliance obligations more carefully.
The immediate focus remains on Tata Sons and its response to the RBI’s November 16 communication. The larger significance, however, lies in the message that regulatory obligations apply even when a company has a long-established private ownership structure.
Key Takeaways
- The RBI reiterated on November 16, 2026, that Tata Sons must comply with Upper Layer NBFC regulations, including mandatory listing.
- Tata Sons was classified as an Upper Layer NBFC in September 2022, with the applicable three-year listing deadline falling on September 30, 2025.
- Tata Trusts, which hold approximately 66 per cent of Tata Sons, oppose the proposed listing, while the Shapoorji Pallonji Group, with approximately 18.37 per cent, supports it.
- The November 26, 2026, board meeting could provide greater clarity on the company’s next steps, although no fresh IPO date has been announced.
Frequently Asked Questions
1. Why is the RBI asking Tata Sons to list its shares?
Tata Sons was classified as an Upper Layer NBFC in September 2022. RBI regulations require companies in this category to list their shares within three years of classification. The applicable deadline for Tata Sons was September 30, 2025.
2. Why does Tata Sons want to avoid a public listing?
Tata Sons has historically operated as a privately held holding company. A public listing would introduce additional disclosure requirements, public shareholder participation and market scrutiny. The company sought to surrender its Core Investment Company registration, but the RBI rejected its application in September 2026.
3. Who are the major shareholders of Tata Sons?
Tata Trusts collectively hold approximately 66 per cent of Tata Sons, while the Shapoorji Pallonji Group holds approximately 18.37 per cent. Other shareholders hold the remaining stake.
4. When could Tata Sons announce its IPO?
There is no officially announced IPO date as of November 17, 2026. The company’s board meeting scheduled for November 26 is an important upcoming development, but an IPO announcement or timeline cannot be assumed.


Leave a comment